
E-Commerce & Online Retail Insurance
Compare quotes from top-rated carriers.
Trusted by +1M small business owners worldwide
No junk mail. No spam calls. Free quotes.
Find your trade
Every online business sells a little differently, and your coverage should reflect that. Start with the page that fits how you sell:

Etsy SellerFrom $20.75/month*
Amazon SellerFrom $20.75/month*
E-commerce and Online RetailFrom $20.75/month*
Drop ShippersFrom $20.75/month*

Written by
You’ve put real work into building your online store. Protecting it should be the easy part. Whether you sell handmade goods on Etsy, run an Amazon storefront, or manage your own site, we’ll help you understand your coverage options, compare quotes from top carriers, and get covered in minutes — so you can get back to business, knowing you’re protected.
Find Your Business Type
Every online business sells a little differently, and your coverage should reflect that. Start with the page that fits how you sell:
- Etsy sellers: Coverage for handmade and curated shops, built around Etsy’s seller terms.
- Amazon sellers: Policies that meet Amazon’s Pro Seller insurance requirements, with instant proof of coverage.
- E-commerce and online retail stores: Protection for your independent online storefront from inventory to customer data.
- Dropshippers: Product liability protection, even if you never touch the stock.
What Insurance Does an Online Business Need?
Selling online comes with its own mix of risks — some physical, some digital. These are the four coverages most online retailers consider, so you can build protection that both fits your business and your budget.
Here’s a quick look at which coverage steps in when:
| Insurance type | What’s covered? |
|---|---|
| General liability | A delivery driver is injured at your home office A competitor claims your ad copied theirs |
| Product liability | A product you sold injures a customer |
| Cyber liability | Your customers’ payment data is breached You’re fined after a data privacy violation |
| Commercial property | Fire or theft wipes out your inventory Your business laptop and equipment are stolen |
A business owner’s policy (BOP) typically combines general liability, product liability, and commercial property — plus lost income if a covered event pauses your sales. More on that below.
General liability insurance (GL) protects your business if a third party alleges that you caused bodily injury, property damage, or personal and advertising injury. For online sellers, that can be a delivery driver tripping over shipping boxes at your home office or a copyright claim over an ad campaign.
Product liability coverage — typically included with GL — helps protect you if a product you sell causes injury, illness, or property damage. Here’s the part that surprises many sellers: As the “seller of record,” you can be held responsible for a defective product, whether you never made, handled, or stored it. That applies to dropshippers and importers, too. With product liability in place, defense costs don’t have to come from your business.
If your store processes payments or collects customer information, cyber liability insurance deserves a close look. Research shows 59% of small- and medium-sized businesses experienced a cyber attack in a single year, and the average cyber claim for a small merchant runs about $205,000. Cyber liability insurance helps cover most costs that typically follow a breach: notifying customers, credit monitoring, forensic investigation, data recovery, legal defense, and regulatory fines — plus lost income while your store is back on its way up.
Your inventory and equipment are the engine of your business. Commercial property insurance, depending on the coverage of your particular policy, helps protect your stock, packaging supplies, and computer gear from fire, theft, and other covered events at your scheduled business premises. If your inventory is stored at a third-party logistics facility or is frequently in transit, you may need Inland Marine coverage.
A business owner’s policy (BOP) bundles GL and commercial property coverage into one package — usually at a better price than buying each separately. It also typically includes business interruption coverage, which helps replace lost income and keeps up with ongoing expenses if a covered event pauses your sales. For many growing online stores, a BOP is the simplest route to broad protection.
Does Amazon or Etsy Require Sellers to Have Insurance?
Sometimes — and it pays to know the rules before the platform comes asking.
Amazon
If your gross sales on Amazon.com top $10,000 in a single month (or if Amazon requests it), Section 9 of the Amazon Services Business Solutions Agreement gives you 30 days to secure commercial liability insurance1. Amazon typically requires that your policy or policies:
- Provide at least $1 million in coverage per occurrence and in the aggregate, written on an occurrence basis.
- Come from a carrier rated A- or better by AM Best or S&P.
- Name “Amazon.com Services LLC and its affiliates and assignees” as additional insureds.
- Match the legal entity name on your Amazon account, with your deductible listed on your certificate of insurance (COI) — $0 for most sellers or up to $10,000 if your gross sales passed $1 million in the previous 12 months.
Once your policy is active, you will need to upload your COI through Seller Central. A nice bonus: With valid insurance on file, Amazon resolves customer property damage and injury claims up to $1,000 on its own, without coming to you for reimbursement.
1These Amazon rules are current as of the date this article was published.
Etsy
Etsy doesn’t require insurance to open a shop, but its Terms of Use ask sellers to defend and indemnify Etsy — including attorneys’ fees and court costs — if a product, listing, or data issue leads to a claim2. And Etsy’s Purchase Protection Program isn’t insurance: It refunds qualifying orders up to $250 and doesn’t cover liability or injury claims. GL with product liability is how sellers cover that ground themselves.
2This Etsy information is current as of the date this article was published.
Does My Homeowner’s Insurance Cover My Online Business?
Usually not — and this is one of the most common surprises for home-based sellers. Homeowners’ and renters’ policies are built for personal risks, so they typically:
- Cap business property coverage at $1,000 to $2,500 at home, and about $250 for business items away from home — rarely enough to replace real inventory.
- Exclude detached garages, sheds, and workshops used for business, along with everything stored inside them.
- Provide no liability coverage for business activities, such as a courier injured while picking up packages.
The good news: A dedicated business policy closes all three gaps, so your inventory, equipment, and personal finances remain protected. It also can keep you in good standing with your home insurer, since an undisclosed home business can put a homeowner’s policy at risk.
How Much Does E-Commerce Insurance Cost?
For e-commerce and online retailers, prices1 start at $27 per month for general liability and $49 per month for BOP coverage.
| Policy | Median Monthly Cost1 |
|---|---|
| General Liability | $27 |
| Business Owner’s Policy (BOP) | $49 |
1Data from Simply Business customers specializing in the identified trade who purchased at least one or a combination of general liability, or BOP policies from July 1, 2025 to December 31, 2025.
What you’ll pay depends on a few key factors, such as:
- What you sell: Lower-risk products like books and apparel cost usually less to insure than higher-risk categories such as supplements, cosmetics, or battery-powered electronics.
- How much you sell: Higher revenue means more exposure, which underwriters typically price in.
- How you fulfill orders: Warehousing your own stock raises property costs; pure dropshipping keeps them low.
- Your coverage choices: Adjusting limits and deductibles lets you match your protection to your budget.
- Where you’re based and your claims history: State litigation trends and a clean record both affect your rate.
The quickest way to know your price is to get a quote — it takes only a few minutes.
How to Get Covered with Simply Business

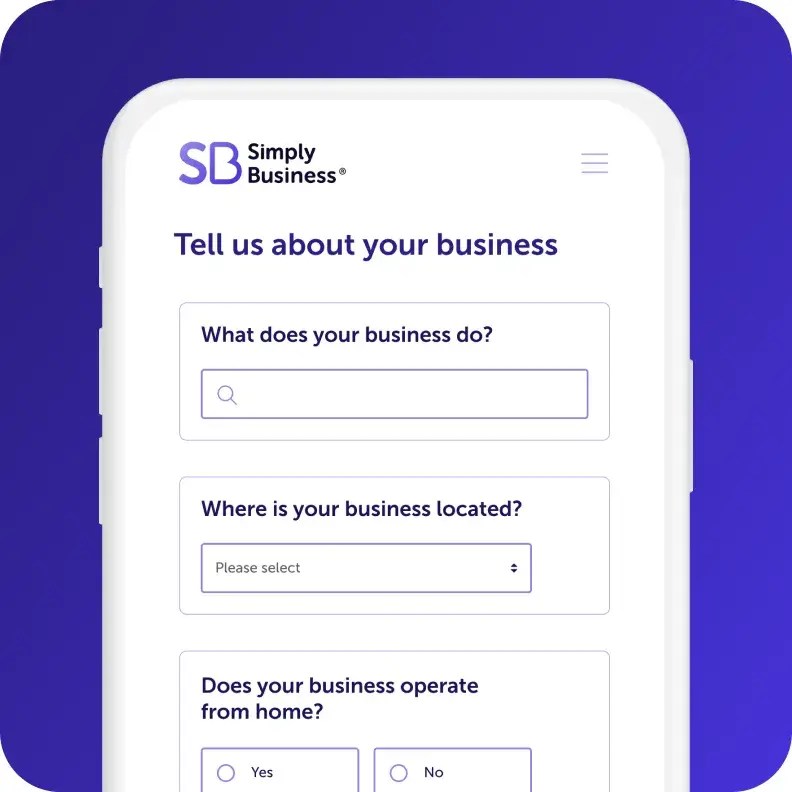
Tell us about your store
One quick application covering your products and sales channels.

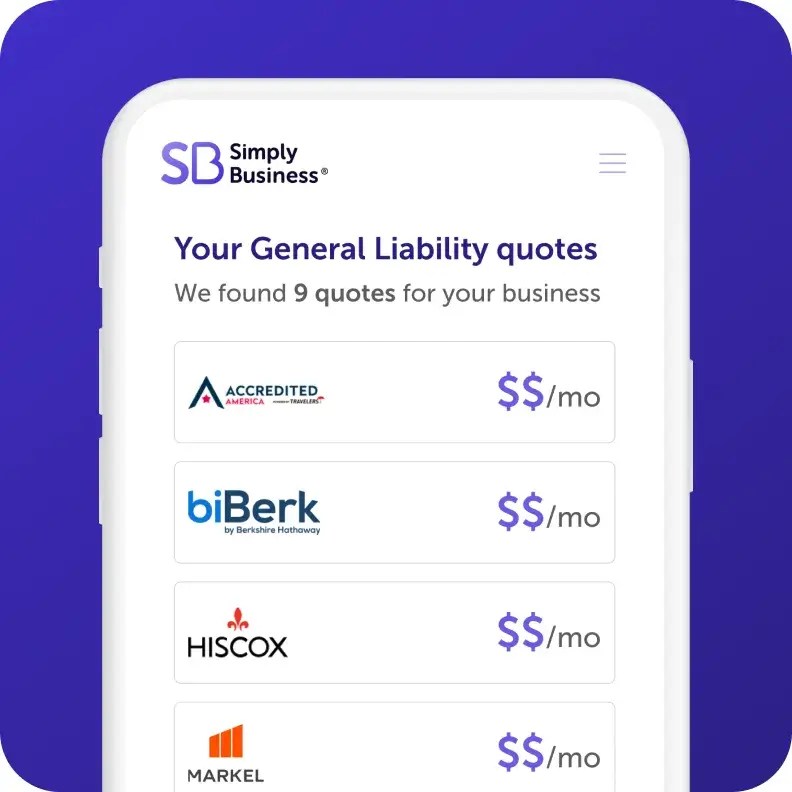
Compare instant quotes
See side-by-side options from top-rated carriers who specialize in small business.

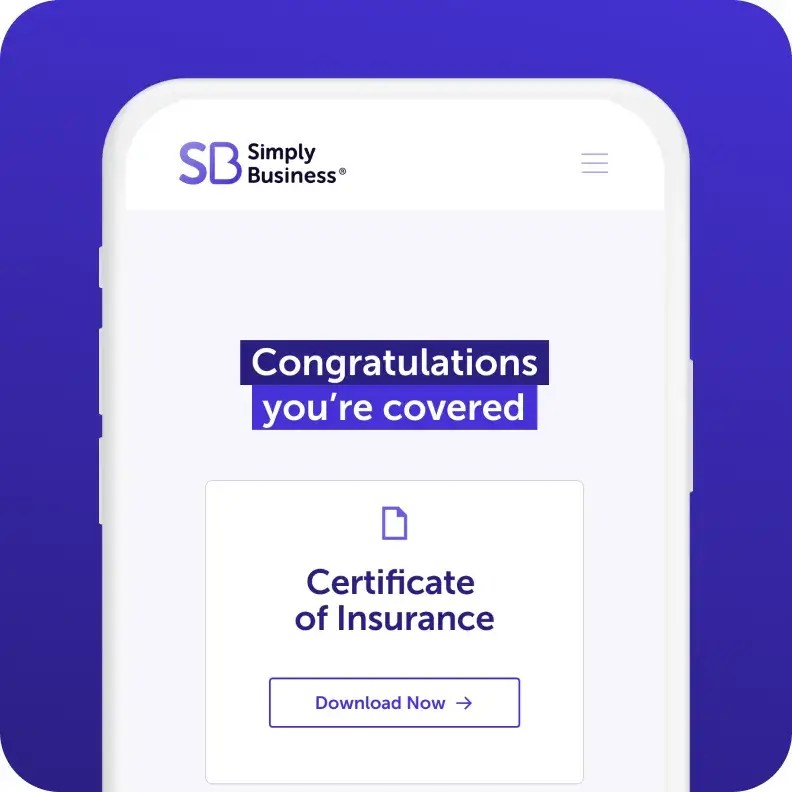
Buy and manage online
Purchase your policy and download your COI right away, then manage everything online 24/7.
Our +1 million customers are big fans. And you will be too.
The process was smooth and easy to complete. I was able to obtain business insurance quickly to meet my marketplace requirements. The online experience was clear and user-friendly.

Trung P.
E-commerce/online retailer, Wyoming
Fast, good service and a reasonable price for the coverage.
Derek M.
E-commerce/online retailer, California
Frequently Asked Questions
In most cases, yes. Online sellers face product liability claims, cyber risks, and inventory losses — and some marketplaces require coverage. Business insurance helps protect your personal assets, meet platform requirements, and give your customers extra confidence in your shop.
General liability (GL) covers everyday business risks, like a visitor injured at your workspace or an advertising injury claim. Product liability — usually included with GL — covers injury, illness, or property damage caused by a product you sell.
If you process payments, collect email addresses, or store customer data, it’s worth serious consideration. Cyber liability insurance helps cover breach response, forensic investigation, legal defense, and lost income while your systems recover.
Amazon requires commercial liability insurance once your gross sales exceed $10,000 in a month, or upon request. Etsy doesn’t require insurance upfront, but its terms require sellers responsible for defending and indemnifying Etsy if a product or listing causes a claim.
Typically, no. Homeowners’ policies cap business property at $1,000 to $2,500 and exclude business liability. A commercial policy is the reliable way to protect your inventory and equipment.
Yes. As the seller of record, dropshippers can be held responsible for defective products under U.S. law, even without ever handling the inventory. Product liability coverage can help cover defense costs and settlements, mitigating your financial risk.
Written by
Feel confident in your choice.
We partner with a range of top-rated carriers and use smart technology to match you with policies that fit your specific business, your risks, and budget.

400+
business types covered

1M+
customers worldwide

18
top-rated carriers
We’ve Got More Helpful Information
4-minute read
Amazon Seller Business Insurance: What You Need to Know
5-minute read
6 Biggest Benefits of Ecommerce Business Insurance
*The displayed price for each product is a monthly estimate calculated from the 10th percentile of relevant policies sold by Simply Business (e.g., General Liability data is used for General Liability estimates). This estimate uses data from relevant policy sales between July–December 2025. Final price and payment terms, which may include an initial down payment, are subject to change based on your state, selected insurance provider, and specific business details.
† Limits may vary by state and nature of your business.
‡ Displayed price is based on the lowest available coverage limit for Equipment and Small Tools policies.
Page last updated: